Gridlock takes hold in Washington as market focus shifts to rates and energy supply
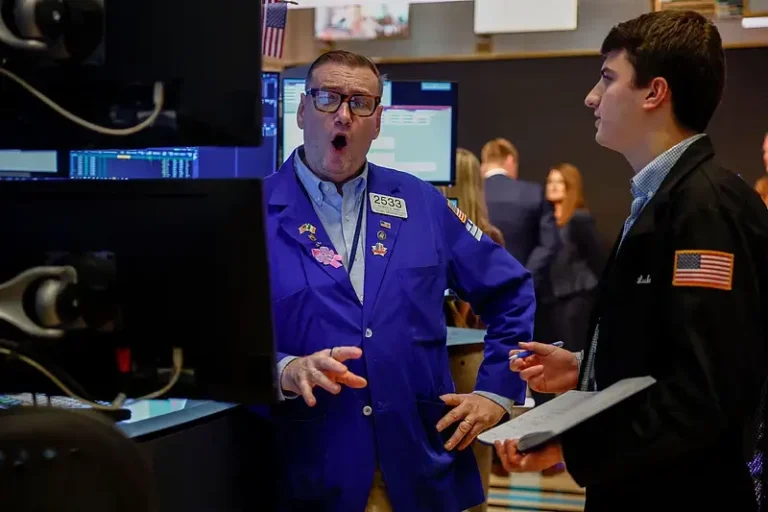
Democratic control of both the House and the Senate establishes a divided government for the final two years of President Donald Trump’s term, restricting large tax and spending changes while shifting primary market drivers to central bank policy and regional geopolitical negotiations. Legislative gridlock narrows the spectrum of unexpected fiscal and regulatory outcomes, forcing corporate treasurers and executive leadership to manage underlying macroeconomic data rather than anticipate major policy overhauls out of Washington.
Legislative Gridlock and Fiscal Boundaries
Divided government reduces the likelihood of rapid fiscal expansion or sweeping changes to code. Julius Baer Fixed Income Analyst Afonso Borges notes that this legislative standstill is inherently market-friendly because it compresses the range of potential fiscal and regulatory shifts. Institutional focus moves away from congressional votes and toward long-term structural risks, specifically the potential for fiscal brinkmanship surrounding the 2027 debt ceiling.
A Democratic Senate offers a counterweight to federal tax and budget initiatives, easing market anxiety over institutional credibility and currency debasement. While a divided congress does not eliminate underlying inflation or fiscal deficits, it restricts legislative momentum that could otherwise accelerate yield movements and pressure the US dollar.
Monetary Trajectories and Commodity Realities
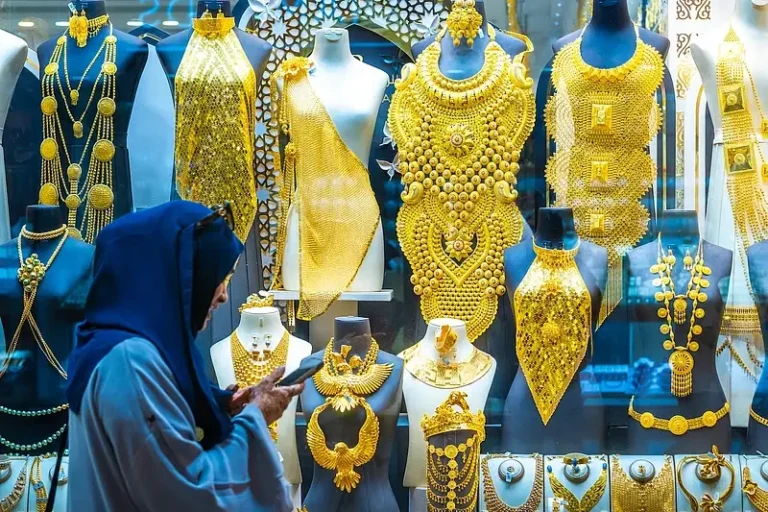
Gold rose 5.2 percent to trade at $4,138 an ounce on Thursday morning, rebounding after slipping below the $4,000 threshold. Century Financial Chief Investment Officer Vijay Valecha characterizes the midterm outcome as a short-term catalyst rather than a structural trend change. Gold remains below its peak from October 2026, while market pricing maintains a strong probability of a Federal Reserve interest rate increase in December. A sustained hold above $4,000 following upcoming employment and inflation data will determine whether bullion secures a lasting recovery.
Historical data analyzed by the World Gold Council shows no consistent link between the political composition of Congress and subsequent gold performance. Initial price movements following previous presidential election cycles quickly normalized. Slower fiscal spending may weigh on long-dated Treasury yields and the US dollar, offering structural support for bullion, though any shift in Fed independence metrics serves as a headwind for debasement hedges.
Energy markets remain tied to physical supply channels and maritime security rather than domestic voting tallies. US crude production operates near record levels, limiting the immediate impact of changes to domestic energy policy. While a Democratic Congress could slow future deregulation initiatives, broader crude dynamics depend heavily on Qatar-led negotiations aimed at reopening the Strait of Hormuz. Continuing attacks on shipping lines limit crude downside, while tighter congressional enforcement of Iranian sanctions threatens to reduce physical supply, directly affecting Gulf energy balances.
Strategic Operational Consequences
For institutional bondholders and corporate treasurers, gridlock simplifies near-term interest rate risk models by capping aggressive fiscal expenditures. Yield curves will react more directly to Federal Reserve policy shifts and inflation readings than to budget proposals.
Energy procurement desks and logistics executives face persistent volatility tied to Middle Eastern maritime trade corridors. Because domestic US crude output is already near capacity, energy pricing remains sensitive to diplomatic talks in Qatar and maritime risk premiums across the Strait of Hormuz rather than legislative votes in Capitol Hill.
Capital allocation within high-tech sectors and AI infrastructure continues to depend on regulatory developments and cost-of-capital trends. The shift in congressional control imposes higher procedural barriers on sweeping regulatory changes, keeping administrative oversight steady while leaving capital costs tied to Federal Reserve policy trajectories.
Market Stability Against Structural Tail Risks
The arrival of a divided government is broadly viewed by financial analysts as a stabilizing mechanism that prevents abrupt regulatory disruptions. However, this policy stability does not eliminate external friction points. Financial markets remain vulnerable to ongoing trade disruptions through the Strait of Hormuz, unpredictable Iranian sanction enforcement, and upcoming fiscal deadlines surrounding the 2027 debt ceiling. Strategic planning must remain focused on physical supply chains and interest rate policy rather than political shifts in Washington.