Dh148.35 Billion Q1 Inflows Push Dubai Real Estate to New Heights
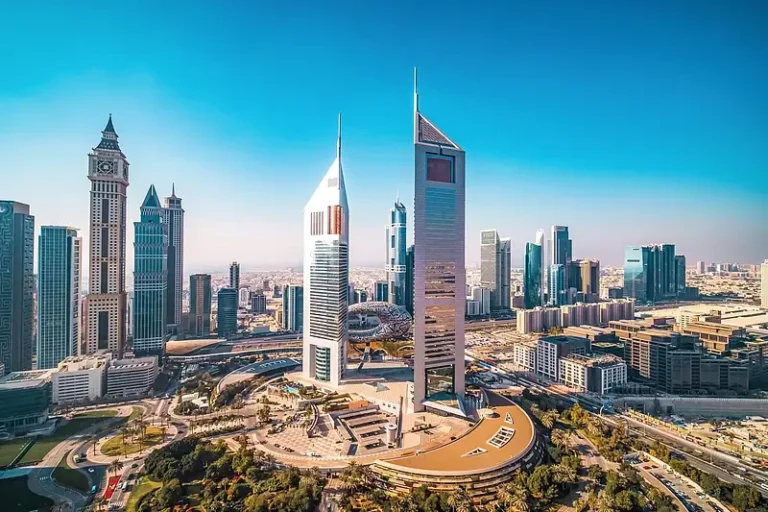
Foreign investment in Dubai real estate reached Dh148.35 billion ($40.4 billion) in Q1 2026 alone, marking a 26 percent year-on-year increase. Nearly 30,000 new global investors entered the market during the first half of the year, underscoring a broader shift toward institutional wealth migration, tax-free income policies, and high rental yields. Total transactions across Dubai crossed Dh574 billion in the first nine months of 2026, registering the second-highest nine-month total on record.
Institutional Capital Shifts the Asset Pipeline
International capital is rapidly reshaping both primary and secondary corridors across the Emirates. In Abu Dhabi, foreign investment in designated investment zones climbed to Dh86.11 billion during the first nine months of 2026, a 131 percent year-on-year surge that accounts for 81 percent of total investment value in those zones. Non-resident individual investment doubled to Dh17.22, while broader regional forecasts point to total GCC residential supply expanding from 6.26 million units in 2025 to 7.28 million units by 2030, anchored heavily by developments in the UAE and Saudi Arabia.
Institutional players are actively moving to capture this expanding pipeline. Nisus Finance Services Co. Ltd expanded its assets under management (AUM) to US$200 million after its Nisus High Yield Growth Fund acquired Adaire 1 & 2, a Grade A residential building in Jumeirah Garden City, from a prominent Emirati institution. The acquisition follows earlier UAE moves by the firm, including Lootah Avenue in Dubai Motor City and Paradise View 1 in Majan.
The Adaire property sits within Meraas’ master-planned regeneration of the historic Al Satwa district, minutes from DIFC, Downtown Dubai, City Walk, and Business Bay. The building is fully pre-leased and features a unit mix aligned with current buyer demand. Across the wider market, one-bedroom apartments made up 42.7 percent of ready apartment sales transactions, while freehold rental contracts rose 6.8 percent year-on-year to reach 298,984.
The upside rests on sustained transaction volumes, steady institutional capital deployment into income-generating assets, and medium-density master plans that keep new supply tightly managed in central districts. The source text documents sustained transactional growth, high occupancy levels, and surging institutional participation without outlining a corresponding downside or market risk.