$3 Billion Q3 GMV Drives talabat to Raise 2026 Outlook Again
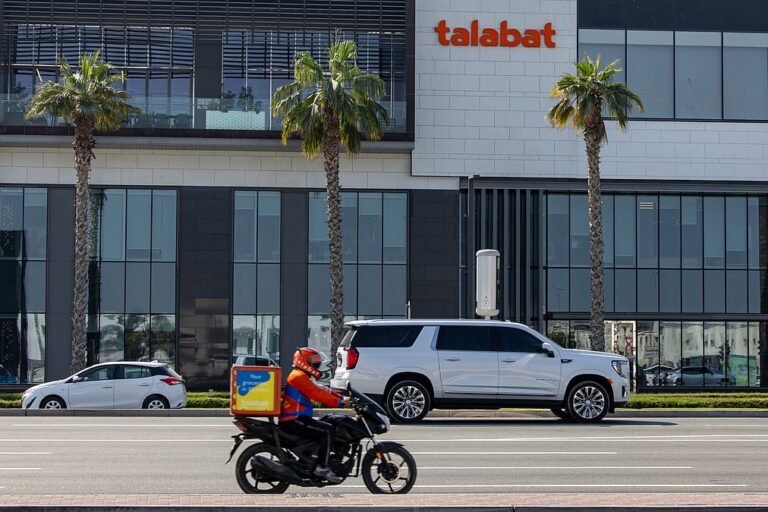
Gross merchandise value reached $3 billion during the third quarter, pushing talabat Holding to upgrade its full-year 2026 financial guidance for the second time. The Dubai-listed delivery operator posted $1.2 billion in quarterly revenue, an 18% year-on-year increase, even as net profit contracted 15% to $102 million due to ongoing expansion outlays.
Expansion Spending Outpaces Margin Growth
The primary driver behind the top-line acceleration was a blend of higher customer acquisition, increased order frequency, and larger average purchase sizes across core operations. Gross merchandise value growth hit 16% overall, and climbed to 17% on a constant-currency basis compared to 15% in the first half of the year.
The GCC remained the dominant anchor, generating $2.3 billion in GMV, a 9% increase year-on-year. Yet the sharper momentum came from outside the immediate region. Non-GCC territories, encompassing Egypt, Jordan, and Iraq, expanded 43% to reach $736 million, lifting their share of total GMV from 20% to 25%. Chief Executive Officer Toon Gyssels pointed to robust momentum across both food and grocery verticals as the catalyst for the upgraded outlook.
The aggressive expansion, however, carried distinct financial friction. The 15% drop in net profit to $102 million stemmed directly from heavy capital deployment into grocery delivery infrastructure and the talabat pro subscription service. Adjusted EBITDA slipped 3% to $150 million, pulling the EBITDA margin down to 5% of GMV from 6% a year prior.
At the same time, operations absorbed some relief from $9 million in budgeted customer incentives that went unspent as food-delivery competition stayed milder than initially projected. Free cash flow climbed 41% to $141 million, reinforcing balance sheet liquidity.
Building on these metrics, management revised its full-year expectations. talabat now forecasts full-year GMV growth of roughly 16% and revenue growth of 19% on a constant-currency basis. Adjusted EBITDA is projected between $560 million and $570 million, with net income targeted at $360 million to $370 million, and free cash flow pegged at $440 million to $450 million.
The company closed September with a net cash position of $711 million. Alongside its operational push, talabat has repurchased 225 million shares, representing 0.97% of its issued capital, for $69 million since initiating its buyback programme, while keeping its $120 million grocery delivery investment framework fully active.