Oil Freight and Insurance Costs Surge Near $50 a Barrel
$49.42 per barrel is the combined cost of tanker freight and marine insurance for moving Middle East crude to East Asia as of October, according to data from the Organisation of the Petroleum Exporting Countries (OPEC).
How Logistics Inflation Rewrites Corporate Budgets
That figure marks a staggering climb from just $3.24 per barrel in January. It means businesses and industrial operators are absorbing an additional $46.18 per barrel in transportation and insurance expenses over a span of just nine months, entirely separate from the baseline price of the crude itself.
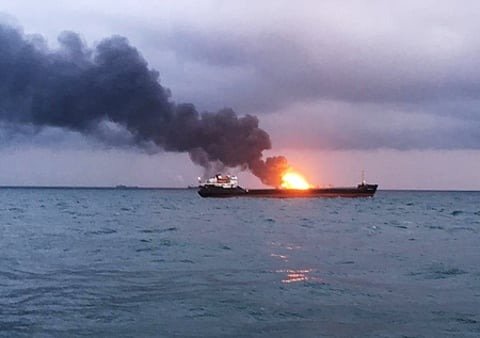
The real weight of the current energy shock is no longer measured by published forward contract delivery rates alone. Instead, logistics expenses have become an independent driver of energy inflation. Even when crude oil prices remain stable, the mechanics of moving that oil to market can drastically raise final delivered costs.
| Logistics Component | January Cost (Per Barrel) | October Cost (Per Barrel) | Change |
|---|---|---|---|
| VLCC Freight Rates | $3.18 | $37.13 | Nearly 12 times higher |
| Marine Insurance | $0.06 | $12.29 | More than 200 times higher |
| Combined Total | $3.24 | $49.42 | Rose from 5% to 30% of total oil costs |
The mechanics behind these numbers reveal a fundamental shift in supply chain economics along the trade route. Very large crude carrier (VLCC) freight rates jumped from $3.18 in January to $37.13 in October. Marine insurance costs recorded an even more extraordinary increase, rising from six cents to $12.29 per barrel.
For corporate operators and logistics managers, the bottom line is severe. Shipping and insurance have transformed from a minor operational overhead into a major balance-sheet item. Where logistics accounted for roughly 5% of total delivered oil costs at the start of the year, those same expenses now consume 30% of the total bill.
OPEC notes that current disruptions to the tanker fleet explain only a small fraction of the increase in freight rates and insurance premiums. This indicates that the cost surge extends far beyond available vessel capacity. For enterprises dependent on energy-intensive operations, manufacturing, and global transport fleets, these structural pressures mean that any easing in crude prices will not automatically translate to lower energy expenditures on the ground.